Residential Mortgage-Backed Securities
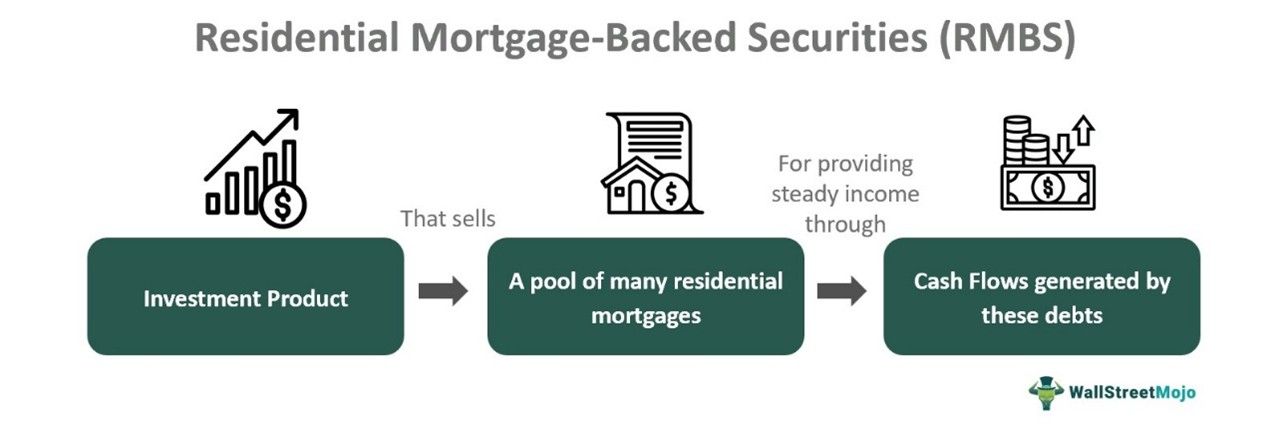
This article is an educational explainer on Residential Mortgage-Backed Securities (RMBS), covering structural mechanics, examples, and trade-offs. It is a definitional guide rather than breaking news or catalyst-driven analysis, making it procedural disclosure material with minimal market-moving implications.
RMBS instruments represent pools of residential mortgages packaged and securitized for investor distribution. The piece likely reviews origination, credit tranching, and cash-flow mechanics—standard instructional content for institutional and retail audiences learning fixed-income architecture. No company earnings, regulatory action, or market event is under examination.
The Financial Services sector—particularly mortgage servicers, government-sponsored entities, and fixed-income managers—maintains structural exposure to RMBS supply and valuation. However, absent new policy, rate guidance, or portfolio repositioning signals, the article serves as reference material rather than a catalyst for sector rotation or equity repricing.
Sector implication: Educational content on RMBS does not alter mortgage market fundamentals, credit spreads, or GSE capital frameworks. Traders and strategists monitoring agency RMBS yields, duration, or prepayment risk would need actual market data or policy shifts—not definitional guidance—to shift positioning.