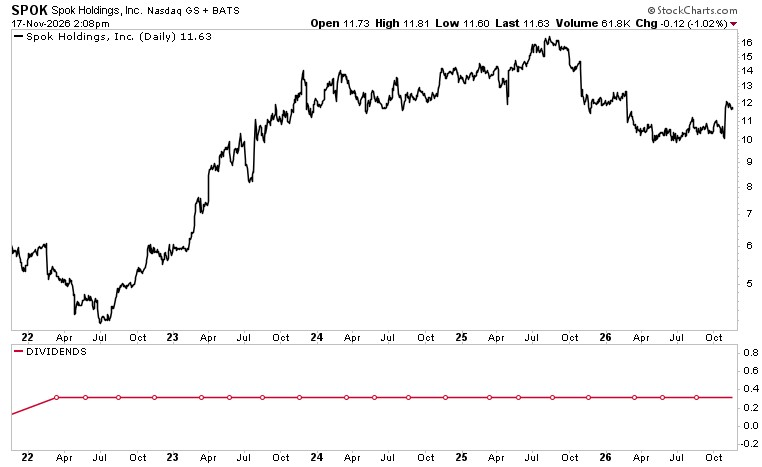
Spok Holdings (SPOK) reported a significant Q3 earnings acceleration, with net income surging over 200% year-over-year. While the magnitude of growth is notable, the article provides minimal detail on drivers—whether this represents operational leverage, one-time benefits, or underlying business momentum remains unclear without deeper context on revenue trends and margin expansion.
The company's 10% dividend yield combined with improved profitability creates a potential valuation compression scenario. High-yield communication/tech stocks often trade at depressed multiples; earnings growth could either justify current pricing or signal prior pessimism was overdone. Balance sheet strength is cited as underpinning distribution sustainability, a material factor for income-focused investors, though dividend safety ultimately depends on consistent cash generation.
As a mid-cap technology stock with communication services exposure, SPOK occupies a niche segment where growth catalysts are often overlooked by institutional capital. The 200%+ earnings jump, if repeatable, would materially alter the investment thesis from yield-play to value-with-growth, though a single quarter rarely confirms trend reversal.
Sector implication: This earnings result is firm-specific and does not signal broad technology or communication sector momentum. The importance lies in whether SPOK's operational improvements reflect structural competitive gains or cyclical strength. Income investors may reassess risk/reward if earnings sustainability appears credible.