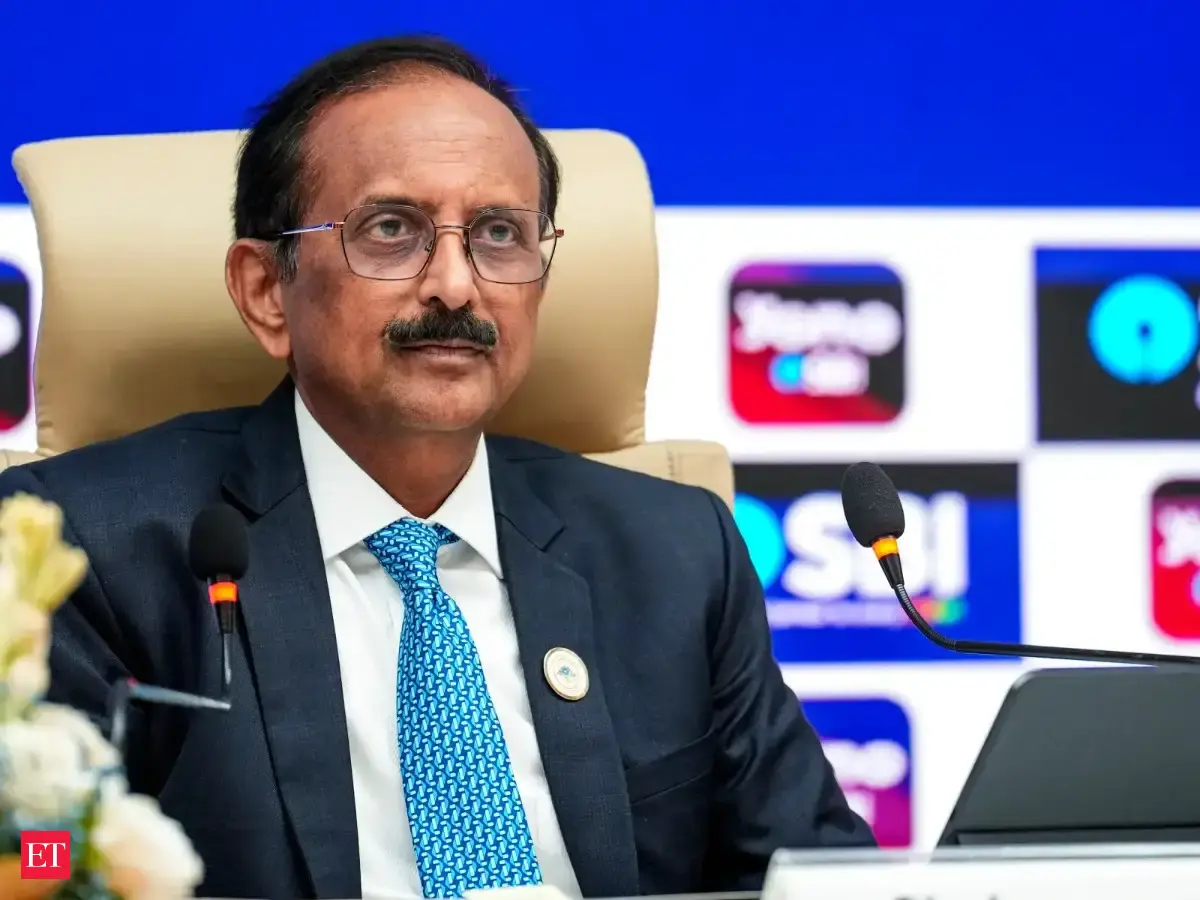
SBI chairman CS Setty's commentary on monetary policy signals a measured tightening cycle ahead for India's banking system. The projected 50 basis points of additional rate hikes through February, coupled with an expected pause, reflects central bank concern about inflation management while attempting to minimize economic disruption. This represents routine forward guidance rather than a surprise policy shift.
Setty's assertion that retail asset quality will remain stable despite rate increases is a key reassurance to investors concerned about loan deterioration in a higher-rate environment. This suggests management confidence in borrower resilience and underwriting standards, though discretionary consumption demand may face headwinds as borrowing costs rise. The distinction between pricing pressure and credit quality deterioration is material for earnings trajectory.
The initiative to expand Yono app functionality toward Jan Dhan account holders reflects competitive positioning in India's retail banking segment and financial inclusion efforts. This operational development addresses market penetration but does not constitute a catalyst-level event for valuation reassessment. It reflects ongoing digital transformation strategy consistent with sector evolution.
Sector implication: Indian financial services face a constrained but stable operating environment. Rate hikes support net interest margins but risk volume compression in discretionary lending. Retail asset quality expectations suggest institutional confidence in credit fundamentals, limiting near-term downside risk to banking sector valuations.